 Ultimate guide
Strategies for Trading High Volatility Earnings Reports
Last Updated: November 7, 2026
Quick Summary
Effective strategies for trading high volatility earnings reports start with reading the expected move from the at-the-money straddle and comparing it to the stock's recent historical post-earnings moves. A ratio above roughly 1.2 favors defined-risk premium selling, while a ratio below roughly 0.8 favors debit spreads or long options. Size every position so a full expected-move gap is survivable, since stops cannot protect against overnight gap risk.
- The at-the-money straddle price divided by the stock price gives the implied move in either direction.
- Pull the last four to eight post-earnings one-day moves and average their absolute values for comparison.
- A ratio near 1.0 is the no-edge zone, and passing is often the honest move.
- Recompute the ratio the day before the report because implied move drifts as the event approaches.
- Cap total earnings-window risk across correlated names reporting in the same week as one position.
Table of Contents
- Why Earnings Reports Trigger High Volatility
- Options Strategies for Earnings Announcements
- Reading the Expected Move in Earnings Options
- Earnings Calendar Trading and Entry Timing
- Whisper Numbers and Earnings Sentiment
- Managing Risk and Position Size Around the Report
- Building Your Earnings Volatility Trade Plan
- Frequently Asked Questions
Why Earnings Reports Trigger High Volatility
Earnings season creates the most concentrated volatility window in the equity calendar, and strategies for trading high volatility earnings reports start with understanding why the crowd gets caught offside. When a company reports, the market reprices every assumption about that business in a single after-hours session. The gap between consensus expectations and market sentiment is where much of the price movement around a report originates.
The Earnings Surprise and the Market Reaction
The earnings surprise, reported results versus consensus estimate, is the single largest driver of the post-report price gap. A beat on revenue and guidance can gap a stock sharply higher at the open; a miss can crater it just as fast. Most of that move happens before regular trading begins, so anyone holding through the report carries overnight gap risk no stop-loss can manage.
Pre-Earnings Volatility and Elevated Option Premiums
Option premiums inflate before an announcement because implied volatility rises to reflect the expected price swing. That elevated premium is the market's forecast of the move, and it cuts both ways: buyers pay more for the same strike, sellers collect more for the same risk. A common mistake is buying a call into earnings without checking whether the premium already bakes in a move larger than the stock typically delivers. For a deeper walkthrough, see our guide to pre-earnings volatility analysis.
Options Strategies for Earnings Announcements
Options strategies for earnings announcements fall into two families: directional bets on which way the stock moves, and volatility bets on how much it moves regardless of direction. Picking the right family matters more than picking the right strike.
Directional Trades: Long Calls and Long Puts
A long call or long put expresses a view on direction, but earnings options carry a hidden cost: even when the stock moves your way, the volatility crush after the report can erase much of the gain. The stock gaps up, your call is in the money, and implied volatility collapses the moment the number is out. If you are weighing this against holding shares outright, our comparison of options versus stock trading during earnings lays out the trade-offs.
Volatility Strategies: Spreads and Premium Selling
Spreads and premium selling flip the equation. A defined-risk spread caps both cost and exposure, which matters when the underlying can gap through your strike overnight. Selling premium into elevated implied volatility lets you collect the inflated premium and profit from the volatility crush, provided the stock stays within your range. Unlimited-risk naked selling is a poor fit for earnings gap risk, so most traders cap it with a spread.
| Strategy | View | Max Risk | Best For |
|---|---|---|---|
| Long call / put | Directional | Premium paid | Strong conviction on direction |
| Debit spread | Directional, capped | Net debit | Directional view with lower cost |
| Credit spread | Range-bound | Spread width minus credit | Selling elevated premium |
| Covered call | Neutral to mildly bullish | Stock downside | Income on shares already held |
Reading the Expected Move in Earnings Options
The expected move is the market's implied forecast of how far a stock will swing around its report, and it is the most useful single number on the options chain. Most retail traders glance at it and move on. The edge comes from turning it into a ratio and letting that ratio pick the strategy.
Calculating the Implied Move from the Straddle
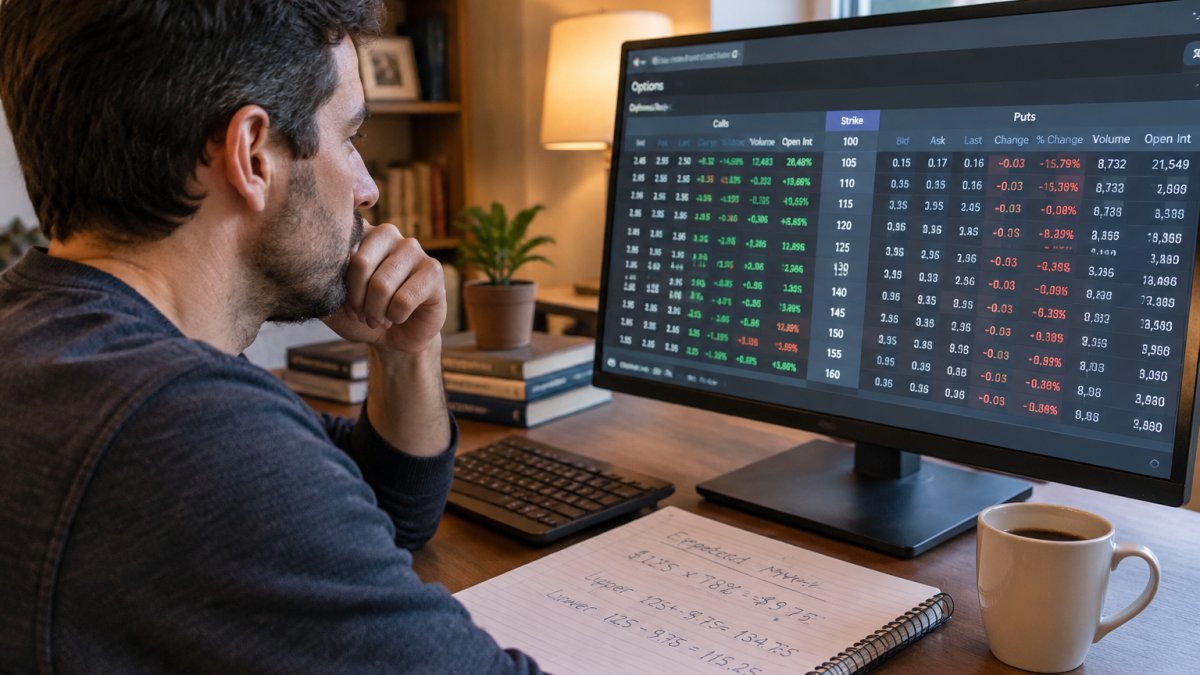
The at-the-money straddle is the cleanest read. Take the nearest expiration that brackets the report, add the at-the-money call price to the at-the-money put price, and divide by the stock price. If a $100 stock has a $4.50 at-the-money call and a $4.00 at-the-money put on the expiration that contains the report, the straddle costs $8.50, so the implied move is roughly 8.5% in either direction.
Comparing Implied Move to Historical Post-Earnings Moves
Pull the stock's last four to eight post-earnings one-day moves, measured close-to-close on the session after the report, and average the absolute values. Then compute the ratio of implied move to that historical average. A ratio well above 1.0 means the options market is pricing a larger swing than the stock has recently delivered, favoring premium sellers and defined-risk credit structures. A ratio below 1.0 means buyers are paying less than the stock's typical reaction, favoring debit structures and outright long options. A ratio near 1.0 is the no-edge zone, and the honest move is often to pass. The same comparison works against realized volatility: if the stock's 20-day realized volatility implies daily moves far smaller than the straddle is pricing, the event premium is rich. This historical-versus-implied ratio is the analysis most retail traders skip, and it is where the edge lives.
Turning the Ratio into a Strategy Decision
Once you have the ratio, the decision tree is short. Ratio above roughly 1.2: favor credit spreads, iron condors, or other defined-risk premium selling, sized so a move to the edge of the expected range is survivable.
Earnings Calendar Trading and Entry Timing
Earnings calendar trading is about sequencing: knowing which names report when, and entering where implied volatility and premium are most favorable to your strategy. Premiums build in the days before the report and collapse immediately after, so buyers generally want to enter early enough to catch the build and exit before the crush, while sellers want to enter once premium is fully inflated.
Whisper Numbers and Earnings Sentiment
Whisper numbers are unofficial, crowd-sourced expectations that often diverge from the published analyst consensus, and that divergence is a genuine sentiment signal. When the whisper number sits above consensus, traders are implicitly expecting a beat; a result that merely matches consensus disappoints a crowd that wanted more. For a step-by-step method, read our guide on how to interpret whisper numbers.
Managing Risk and Position Size Around the Report
Risk management around earnings starts with accepting that gap risk cannot be stopped out. A stop-loss does not protect you when the stock opens 15% lower than where you closed the night before, and a stop order entered for the regular session can fill far from its trigger if the opening print gaps through it. The practical response is to size for the gap, not for the stop.
Sizing for Gap Risk, Not Stop Risk
Start with the expected move you calculated from the straddle and assume the stock can move that far against you, or a bit more, before you can react. If a position sized at your normal risk budget would lose more than you can tolerate on a full expected-move gap, cut the size until it would not. A common pattern is to risk no more than a small fraction of account equity on any single report, treated as a hard ceiling rather than a target.
Execution Risk: Spreads, Slippage, and the Opening Auction
Thin options with wide bid-ask spreads quietly eat your edge. Before you commit, check the bid-ask spread as a percentage of the option's mid price and favor strikes and expirations with tight markets and open interest. Avoid market orders into a fast tape; use limit orders and accept that a fill may not come. After the report, the opening auction and first several minutes of regular trading are where slippage is worst, because quotes are wide and price discovery is still happening.
Portfolio-Level and Correlated Earnings Exposure
Single-position risk is only half the problem. Several names in the same sector often report in the same week and react to the same macro backdrop, so a handful of positions can behave like one oversized bet. Add up the capital at risk across all reports in the same window, group it by sector and correlation, and cap the aggregate the same way you cap a single name.
Post-Report Trade Management and Gap Risk
Decide before the report how you will handle an overnight gap: exit at the open, hold for a target, or scale out in pieces. If you plan to exit, know that the opening print may be far from the last close and a stop order will not save you. Our earnings season risk management checklist walks through sizing and exposure step by step.
Building Your Earnings Volatility Trade Plan
A repeatable trade plan beats a good hunch every time. Before any earnings trade, run this checklist:
- Confirm the report date and whether it is before or after the market close
- Read the expected move from the at-the-money straddle
- Compare implied move against the stock's recent historical post-earnings moves
For traders assembling their first plan, our beginner's guide to trading earnings reports covers the end-to-end process. Execution matters as much as the plan: favor liquid strikes and avoid market orders into a fast tape.
Earnings volatility rewards preparation and punishes improvisation. The traders who consistently navigate these reports compare implied moves to history, size positions for gap risk, and read sentiment before the crowd does.
Frequently Asked Questions
What are the best strategies for trading earnings reports?
There is no single best strategy, because the right approach depends on your market view and risk tolerance. Directional traders use long calls or long puts when they expect a strong move in one direction. Traders who expect a large move but are unsure of direction use straddles or strangles. Traders who expect volatility to fall after the report sell premium through credit spreads or covered calls. Each setup carries different risk, so match the strategy to your thesis and position size before the report.
How do you trade options before an earnings announcement?
Start by checking the expected move priced into the options chain, which tells you how large a swing the market is already anticipating. Compare that figure to the stock's historical post-earnings moves to judge whether options look expensive or cheap. Decide whether you are buying or selling volatility, choose an expiration that extends past the report date, and size the position so a total loss of premium stays within your risk budget. Enter before the report only when your thesis justifies the elevated premium.
Why does implied volatility rise before earnings?
Implied volatility rises before earnings because traders expect a larger-than-normal price swing once the results are released. Demand for options increases as traders position for the event, and option prices rise to reflect the wider range of possible outcomes. This is why options premium is elevated in the days before a report. The effect is strongest in the final week before the announcement and tends to reverse quickly once the numbers are public.
What happens to implied volatility after an earnings report?
Implied volatility typically collapses once the report is released and the uncertainty is resolved. This is known as volatility crush. Even when the stock moves in your favor, a long option can lose value if the drop in implied volatility outweighs the gain from the price move. Traders who buy options before earnings need the stock to move further than the expected move to profit. Traders who sell premium aim to capture that crush, but they take on larger directional risk.
How can traders estimate a stock's expected move for earnings?
The expected move is commonly estimated from the at-the-money straddle price for the expiration that covers the earnings date. Add the call and put premiums at the strike nearest the current stock price, and that total approximates the market's implied one-standard-deviation move. You can also multiply the stock price by implied volatility and adjust for the number of days until expiration. Compare the result to the stock's average historical post-earnings move to see whether options are pricing in more or less movement than usual.
Is it better to buy or sell options before earnings?
Neither is universally better. Buying options gives you defined risk, but you pay elevated premium and must overcome volatility crush. Selling options collects that premium, but exposes you to gap risk and potentially large losses if the stock moves sharply against you. The decision comes down to whether you believe the market is overpricing or underpricing the expected move. Many experienced traders compare implied moves to historical moves and only take the side where the odds appear favorable.
How do you manage risk when trading earnings volatility?
Keep position size small relative to your account, because earnings gaps can jump past stop-loss levels. Define your maximum loss before entering, whether that means limiting premium paid or setting a stop on a spread. Avoid concentrating several correlated positions in the same sector during the same earnings week. Consider exiting part of the position before the report to reduce exposure, and review each trade afterward so you can measure what worked and adjust your process.